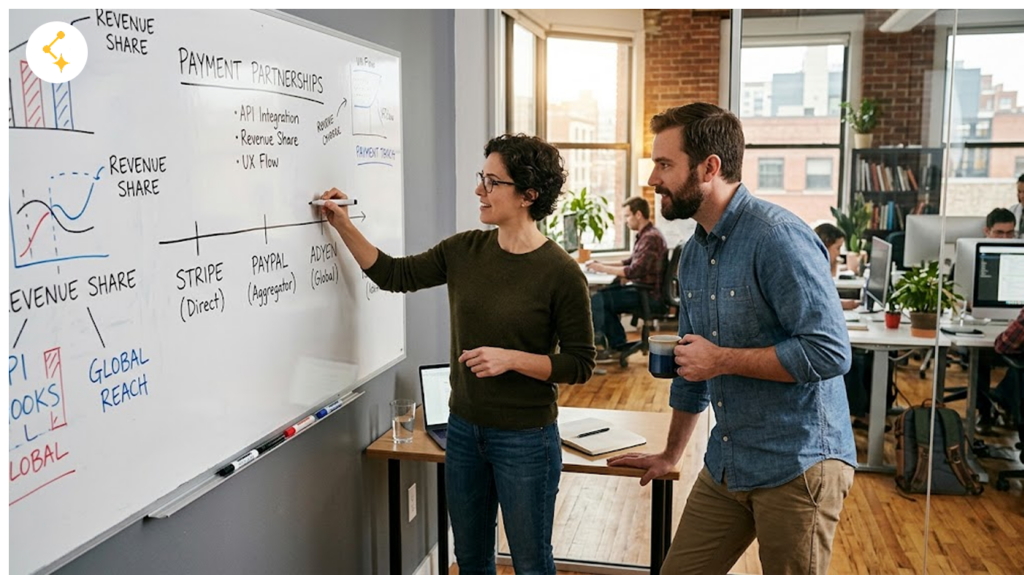
Almost every vertical software company ends up in the payments business eventually. Your customers need to get paid, your product sits at the point where that happens, and sooner or later someone on the leadership team asks why the platform isn’t earning anything from the volume flowing through it.
What is less obvious is that there is not one answer to that question. There are three, and they sit on a spectrum. Each one asks something different of your product, your team, and your customers, and each one delivers a very different share of the economics back to you. Picking the wrong one is rarely fatal, but it usually means leaving money and control on the table for years while looking busy.
This is a plain-language guide to the three models: referral, integrated, and embedded. It is written for founders, product leaders, and finance leaders at vertical SaaS companies who want to understand the options before a vendor frames them.
The referral model: someone else’s product, a small slice of the revenue
In a referral partnership, you point your customers to a processor. The processor signs them, underwrites them, supports them, and pays you a commission on what they process. You are, in effect, a lead source.
The appeal is obvious. There is almost nothing to build. A logo on a partner page, a link inside the product, maybe a one-line integration for a hosted checkout, and you are live. Your team stays focused on the core product and payments becomes someone else’s problem.
The cost is everything you gave up to make it that easy. Your customer now has a second vendor with its own contract, its own pricing, its own support desk, and its own opinion about how checkout should look. You have little visibility into their processing and almost no ability to fix a problem when one shows up. If your customer churns from the processor, you usually stop earning. And if the processor decides to change the commission, there is not much leverage on your side of the table.
Referral is a reasonable starting point for early-stage platforms or for companies where payments are truly peripheral to the product. It becomes a liability the moment payments start to matter to your customers’ experience, because you have outsourced the thing they will judge you on.
The integrated model: your interface, their rails
The integrated model is where most vertical software companies live today. You build a proper technical integration with a processor or gateway, so that payments happen inside your product rather than on someone else’s page. Invoices get paid in your invoicing screen. Card on file lives in your customer record. Reports show up in your dashboard.
Your customers still sign a merchant agreement with the processor, and underwriting, funding, and risk still happen on the processor’s side. But the day-to-day experience is yours, and the revenue share is usually meaningfully better than a referral commission because you are delivering more of the value.
This is a real step up. It is also where a lot of companies stall, because the integrated model has a ceiling that only becomes visible once you are inside it.
Onboarding is the first place you feel it. The merchant application belongs to the processor, so your customer fills out a form you did not design, waits for a decision you cannot see, and calls you when something goes wrong with a process you do not control. Support is the second. When a payout is late or a transaction is declined, your customer calls the company whose name is on the screen, which is you, and you end up relaying tickets between two support teams. Pricing is the third. You can influence what your customers pay, but you cannot set it, bundle it, or change it without a negotiation.
Integrated payments gets you into the room. It does not give you the keys.
The embedded model: payments as part of the product you own
In the embedded model, payments stops being a partnership and becomes a feature. The merchant relationship is yours. Onboarding happens in your product, on your terms, with a flow you designed. Pricing is yours to set and package. Support is yours end to end. And the economics shift accordingly, because you are now the one delivering the full payments experience rather than renting a piece of it.
Historically, getting here meant becoming a payment facilitator yourself: registering with the card networks, standing up underwriting and risk operations, carrying the compliance burden, and building the money movement infrastructure. For most vertical software companies that is a multi-year detour away from the product they actually want to build. We have written about the real cost of that path separately, and the short version is that it is larger and more permanent than it looks from the outside.
What has changed is that the embedded model no longer requires becoming a PayFac. A PayFac as a Service arrangement gives you the ownership and control of the embedded model while a partner carries the registration, the underwriting operations, and the compliance infrastructure underneath. You own the customer, the experience, and the pricing. They own the plumbing.
That distinction matters because it collapses what used to be a hard tradeoff. You no longer have to choose between the low effort of integrated payments and the control of owning the whole stack. You can have the second without paying the full price of building it.
How to tell which model you are actually in
Vendors are not always precise about this, and plenty of arrangements marketed as embedded are integrated with a nicer logo. A few questions cut through the language.
Who does the merchant sign with? If your customer signs a merchant agreement with a third party, you are integrated, not embedded, whatever the deck says.
Who designs and owns the onboarding flow? If your customer leaves your product, or fills out a form you cannot change, to get approved, that is a signal.
Who sets the price? If you have to ask permission to change what your customers pay, you are not the one in control of the economics.
Who does the customer call? If the answer is the processor, the customer relationship is not fully yours. If the answer is you but you cannot resolve the issue without escalating to the processor, it is only partly yours.
What happens to the revenue if the relationship ends? Referral and integrated arrangements typically leave you with little when a merchant or processor moves on. In a true embedded model the merchant is your customer, and the portability of that relationship is worth understanding before you sign anything.
Choosing the right model for where you are
There is no universally correct answer, but there is usually a correct answer for a given stage.
If payments are peripheral and your team is small, referral is fine, provided you go in knowing it is a placeholder rather than a strategy.
If payments are central to your customers’ workflow and you have engineering capacity, integrated is the minimum viable position. It gets the experience into your product and starts building the muscle. The risk is treating it as the finish line.
If payments have become a real part of how your customers run their business, and a real part of how you plan to grow, embedded is where the model wants to go. The question is only whether you build the infrastructure yourself or partner with someone who already has it. For most vertical software companies, the ISV partnership route is the shorter path by a wide margin, and it leaves your roadmap intact.
The pattern we see most often is not a company choosing badly. It is a company choosing correctly for the stage it was in three years ago and never revisiting the decision. Payments models are not permanent. If your customers have grown, your volume has grown, and your product has grown, the arrangement that made sense at the start is probably the one holding you back now.
A shorter path to the embedded model
For Constellation Software and Jonas operating companies, CSIPay is built to deliver the embedded model without the PayFac build. It is PCI DSS Level 1 certified, covers the US and Canada, and is already live across more than 4,000 merchants and a growing network of partners. If you are trying to work out which model you are in today and where you want to be, talk to the partnerships team. That conversation is usually shorter and more useful than another vendor deck.